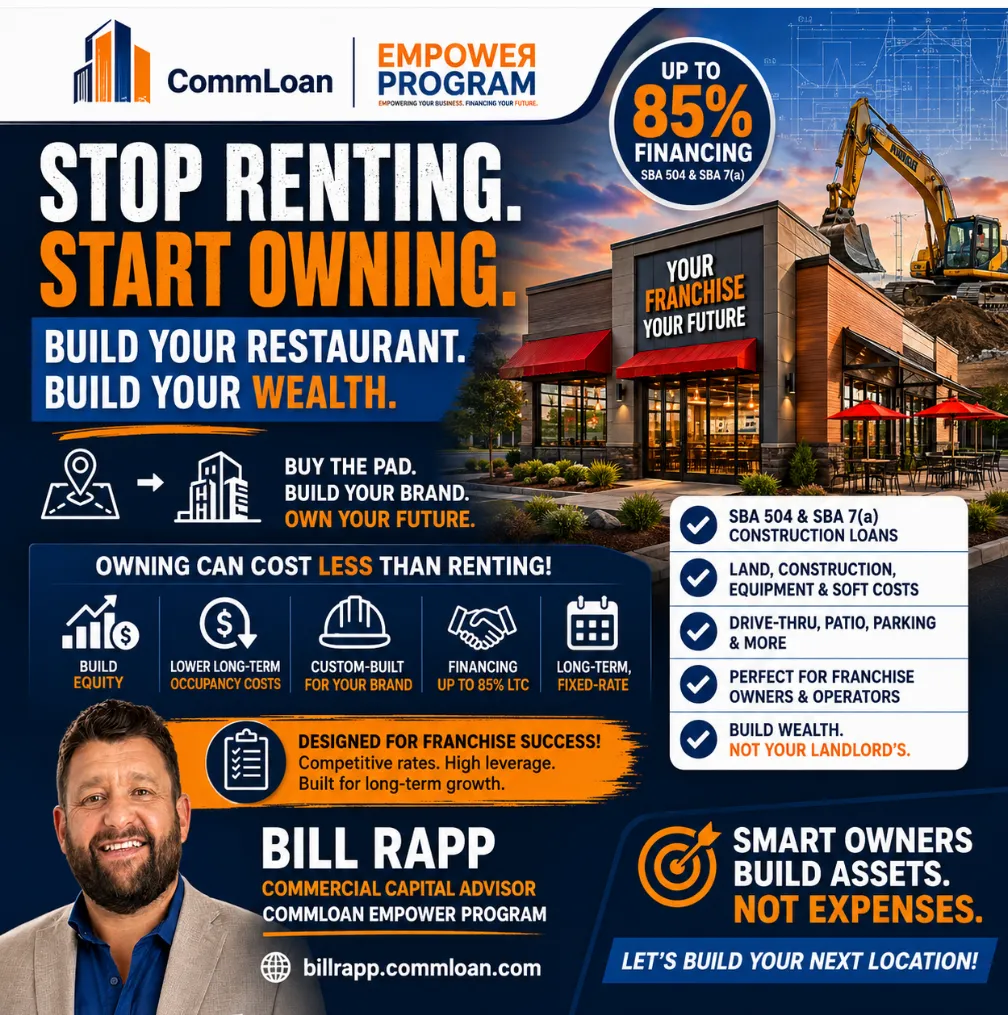
💰 Stop Renting Restaurant Space: Buy the Land, Build the Restaurant & Build Equity with SBA Construction Loans 🔑

🍔 Restaurant Construction Loans for Franchisees: Build Your Own Location with SBA 504 & SBA 7(a) Financing 🏗️

July 15, 2026•4 min read

🍔 Restaurant Construction Loans for Franchisees: Build Your Own Location with SBA 504 & SBA 7(a) Financing 🏗️

💰 Stop Renting Restaurant Space: Buy the Land, Build the Restaurant & Build Equity with SBA Construction Loans 🔑


Restaurant Construction Loans for Franchisees: Why Owning Your Building Can Cost Less Than Renting

For many restaurant franchisees, the default strategy has always been to lease a second-generation restaurant space. The logic seems simple—it already has a kitchen, dining room, and utilities, so opening should be faster.

But what if buying your own restaurant pad and constructing a brand-new building actually resulted in a similar—or even lower—monthly payment while allowing you to build long-term wealth?

With today's SBA 504 and SBA 7(a) construction financing programs offering up to 85% Loan-to-Cost (LTC), many franchise owners are discovering that owning their real estate may be one of the smartest business decisions they ever make.

Why Franchisees Continue to Rent

Most franchise operators lease because they believe:

·Construction is expensive.

·Banks require massive down payments.

·Owning real estate ties up too much capital.

·Leasing is easier.

While those assumptions were often true years ago, today's SBA lending programs have changed the equation.

The Hidden Cost of Leasing a Second-Generation Restaurant

Second-generation restaurant space isn't always a bargain.

Many locations require:

·New HVAC systems

·Hood modifications

·Plumbing upgrades

·ADA improvements

·Electrical upgrades

·New franchise branding

·Parking lot repairs

·Roof repairs

·Landlord approval delays

Even after spending hundreds of thousands of dollars in tenant improvements, you still don't own the building.

You're simply increasing the value of someone else's property.

Why Buying a Restaurant Pad Makes Sense

Purchasing land and building specifically for your franchise offers several advantages.

Build Equity Instead of Paying Rent

Each monthly payment reduces principal while your property may appreciate over time.

Instead of creating wealth for a landlord, you're creating wealth for your business.

Design Around Your Brand

Every major franchise has unique specifications.

Building from the ground up allows you to optimize:

·Drive-thru layout

·Kitchen efficiency

·Customer flow

·Parking

·Patio seating

·Future expansion

Lower Long-Term Occupancy Costs

In many markets, an SBA-financed owner-occupied restaurant can produce monthly occupancy costs that are competitive with—or lower than—leasing a premium second-generation location.

The result is predictable long-term occupancy expenses without the uncertainty of lease renewals and escalating rental rates.

SBA 504 Restaurant Construction Loans

The SBA 504 program is designed for owner-occupied commercial real estate.

Typical benefits include:

·Up to 85% Loan-to-Cost

·Long-term fixed-rate financing on the SBA portion

·Fully amortizing structure

·Competitive interest rates

·Ideal for established franchise operators

These loans are excellent for:

·Fast food franchises

·Casual dining

·Quick-service restaurants (QSR)

·Coffee shops

·Drive-thru concepts

·Medical food concepts

SBA 7(a) Construction Loans

The SBA 7(a) program provides additional flexibility.

It may finance:

·Land acquisition

·Site development

·Building construction

·Equipment

·Furniture

·Working capital

·Soft costs

This flexibility makes SBA 7(a) especially attractive for newer franchise operators or projects with additional capital needs.

Eligible Restaurant Types

Construction financing is available for many franchise concepts, including:

·Chicken restaurants

·Burger concepts

·Pizza franchises

·Coffee shops

·Sandwich shops

·Mexican restaurants

·Smoothie concepts

·Breakfast restaurants

·Ice cream stores

·Specialty food franchises

What Lenders Want to See

Lenders typically evaluate:

·Franchise experience

·Management experience

·Personal liquidity

·Credit profile

·Business plan

·Franchise approval

·Project budget

·Construction timeline

A strong development team and realistic financial projections can significantly improve approval odds.

Why Work with a Capital Advisor?

Every lender evaluates restaurant construction differently.

Some specialize in:

·Restaurant construction

·Ground-up development

·SBA lending

·Franchise financing

·Multi-unit operators

Rather than approaching one bank, experienced Capital Advisors compare financing across a broad network of lenders to identify the structure that best fits your project.

Final Thoughts

Restaurant real estate can become one of the most valuable assets a franchise owner ever acquires.

Instead of spending years paying rent to someone else, today's SBA construction financing programs allow many operators to build equity while controlling their occupancy costs.

If you're planning your next restaurant location, don't automatically assume leasing is the cheapest option.

Owning may cost less than you think—and create significantly greater long-term wealth.


Bill Rapp, CCIM
Director | CommLoan

📞 281-222-0433
📧
[email protected]
🌐
https://billrapp.commloan.com/

🌐 https://HoustonCommercialMortgage.com/

Commercial Real Estate Financing Nationwide


https://billrapp.commloan.com/

https://empower.commloan.com/

https://author.billrapponline.com/

https://www.amazon.com/dp/B0F32Z5BH2

https://veed.cello.so/FOmzTty6oi9

https://buymeacoffee.com/vikingente3

https://creplaybookseries.billrapponline.com

https://creplaybook.billrapponline.com/


©Bill Rapp, CCIM - Director - CommLoan

restaurant construction loanSBA 7(a) construction loanSBA 504 restaurant loanfranchise financingrestaurant development loanRestaurant real estate financingCommercial construction loansbuy restaurant propertyGround-up restaurant financingrestaurant financing loanrestaurant franchise financingSBA commercial real estate loansSBA commercial property loansSBA 7(a) loansSBA 504 loansSBA commercial mortgageSBA business property financingSBA commercial loan requirementsSBA real estate financingSBA loans for business ownersSBA commercial lendingSBA 7(a) commercial real estate loanSBA 504 commercial real estate loanSBA 7(a) vs SBA 504SBA 504 loan requirementsSBA 7(a) loan requirementsSBA 504 loan ratesSBA 7(a) loan ratesSBA 504 loan benefitsSBA 7(a) loan benefitsSBA 504 loan structureSBA commercial real estate down paymentSBA loan 10 percent downSBA commercial loan down payment requirementslow down payment commercial property loansSBA commercial loan eligibilitySBA owner occupied real estate loansSBA owner occupancy requirementsSBA commercial loan credit requirementsSBA commercial loan DSCRSBA loan qualification requirementshow to get an SBA commercial real estate loanhow to buy commercial property with an SBA loanhow to qualify for SBA commercial financinghow to apply for an SBA 504 loanhow to apply for an SBA 7(a) loanhow to finance a business property purchasehow to purchase an office building with an SBA loanhow to buy a warehouse with an SBA loanhow to finance owner occupied commercial real estateSBA commercial property loan applicationSBA loans for medical office buildingsSBA loans for dental officesSBA loans for warehousesSBA loans for retail buildingsSBA loans for office buildingsSBA loans for manufacturing facilitiesSBA loans for industrial buildingsSBA loans for restaurantsSBA loans for automotive repair shopsSBA loans for professional office buildingsSBA commercial construction loansSBA 504 construction financingSBA 7(a) construction loansSBA commercial renovation loansSBA business expansion financingSBA commercial property refinancingSBA 504 refinance programSBA 7(a) refinance loansSBA equipment and real estate financingSBA commercial building acquisition loansSBA commercial loans vs conventional loansSBA 504 vs conventional commercial mortgageSBA 7(a) vs conventional business loanSBA financing vs bank financingSBA commercial mortgage interest ratesSBA loan amortization termsSBA commercial loan closing costsSBA loan prepayment penaltiesSBA commercial loan repayment termsSBA commercial loan approval processSBA loans for small businessessmall business commercial real estate financingcommercial property loans for entrepreneursbusiness owner commercial mortgagecommercial real estate loans for startupscommercial loans for established businessesowner occupied commercial mortgagesmall business property purchase loanscommercial real estate financing for business expansioncommercial mortgage broker for small businessesSBA loan cash flow requirementsSBA commercial loan debt service coverageSBA loan personal guarantee requirementsSBA commercial real estate appraisalSBA commercial loan environmental requirementsSBA loan documentation checklistSBA commercial loan approval timelineSBA commercial loan lender requirementsSBA commercial loan underwritingSBA commercial real estate loans TexasSBA commercial loans HoustonSBA commercial real estate financing Katy TXSBA 504 lenders TexasSBA 7(a) lenders Houstoncommercial mortgage broker Houston TexasSBA financing for Texas business ownersSBA commercial property loans West HoustonCommLoan commercial real estate financingCommLoan Empower ProgramBill Rapp CCIM commercial financing
Bill Rapp - Commercial & Residential Mortgage Broker

Bill Rapp - Commercial & Residential Mortgage Broker

Whether you're a first-time homebuyer, a seasoned investor, or a business owner with ambitious plans, securing the right financing is crucial. At Medallion Funds, we take the guesswork out of mortgages, offering a comprehensive suite of residential and commercial loan options to fit your unique needs. Looking for Your Dream Home? We understand the excitement and challenges of navigating the residential real estate market. Our experienced mortgage brokers will guide you through every step, from pre-qualification to closing. We offer a variety of loan programs to suit your financial situation, including: • Fixed-rate mortgages: Offering stability with predictable monthly payments. • Adjustable-rate mortgages (ARMs): Providing competitive rates for a set period. • FHA loans: Making homeownership accessible with lower down payments. • VA loans: Rewarding veterans with attractive rates and flexible terms. Investing in Your Business Future? Growth often requires capital, and we can help you unlock the potential of your commercial property. Our brokers specialize in a wide range of commercial loan options, including: • Purchase loans: Financing the acquisition of new buildings or land. • Construction loans: Facilitating the development of your project. • Refinance loans: Restructuring your existing mortgage for better terms. • SBA loans: Providing access to government-backed financing for qualified businesses. The Medallion Funds Difference: We go beyond simply finding a loan. We take the time to understand your goals and develop a personalized strategy. Here's what sets us apart: • Expertise: Our brokers have a deep understanding of both residential and commercial lending. • Competitive Rates: We leverage our strong lender relationships to secure the best possible terms. • Streamlined Process: We handle the paperwork, keeping you informed every step of the way. • Exceptional Service: We're committed to providing you with a positive and stress-free experience. Ready to Take the First Step? Contact Medallion Funds today for a free consultation. Let's discuss your financing needs and help you achieve your dreams!

LinkedIn logo icon
Instagram logo icon
Youtube logo icon
Back to Blog