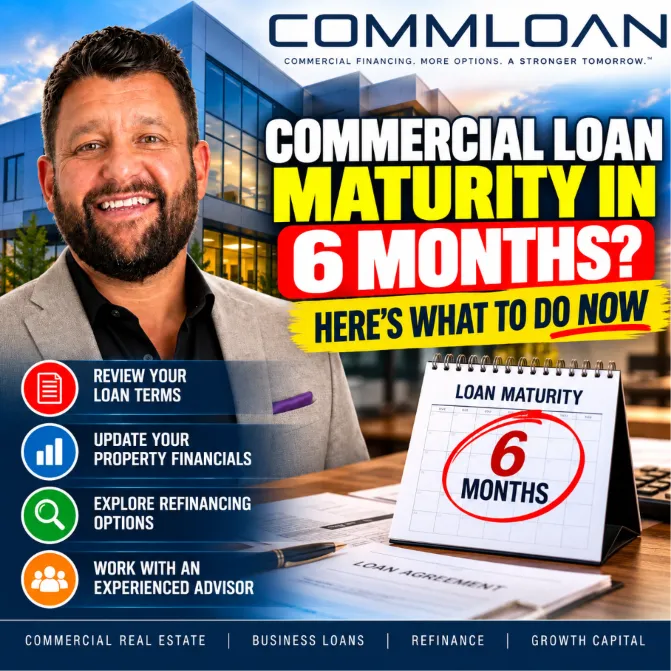
🚨 Commercial Loan Maturity in 6 Months? Here's What to Do Now Before Your Balloon Payment Comes Due! 🏢
🚨 Commercial Loan Maturity in 6 Months? Here's What to Do Now Before Your Balloon Payment Comes Due! 🏢
⏰ Commercial Mortgage Refinancing: 7 Critical Steps to Take Before Your Loan Matures! 💰
___________________________________________________________
Commercial Loan Maturity in 6 Months? Here's What to Do Now
By Bill Rapp, CCIM | CommLoan Empower Program
If your commercial real estate loan matures in the next six months, the clock is already ticking.
Unlike most residential mortgages, many commercial real estate loans have relatively short terms, often five, seven, or ten years, with a balloon payment due at maturity.
That means your remaining loan balance may become payable in full—even if you've made every monthly payment on time.
For commercial property owners, approaching loan maturity without a refinancing strategy can create significant financial challenges.
Higher interest rates, tighter underwriting standards, changing property values, and reduced cash flow can all affect your ability to refinance.
The good news? Six months can provide a valuable opportunity to evaluate your options, prepare your financial package, and develop a financing strategy before your existing loan expires.
Here's what commercial real estate investors and business owners should do now.
What Happens When a Commercial Real Estate Loan Matures?
When a commercial mortgage reaches its maturity date, the remaining principal balance generally becomes due unless the loan documents provide for an extension, renewal, or other arrangement.
Consider this example:
Original commercial loan: $2,000,000
Loan term: 5 years
Amortization schedule: 25 years
Remaining principal at maturity: Approximately $1,770,000
Balloon payment due: Approximately $1,770,000
Illustrative example assuming a 6.5% fixed rate, monthly payments, and no principal curtailments.
Even though the borrower has made regular monthly payments for five years, a substantial balance remains.
Unless the borrower has sufficient liquidity to repay that balance, refinancing or another repayment strategy will be necessary.
This is why commercial loan maturity planning should begin well before the actual maturity date.
Why Refinancing May Be More Difficult Today
Commercial real estate refinancing is not automatically guaranteed simply because a borrower has a strong payment history.
Lenders typically evaluate the transaction based on current property performance, borrower qualifications, collateral value, and prevailing credit standards.
Several factors can create refinancing challenges.
1. Higher Interest Rates
A property financed several years ago may have benefited from a lower interest rate.
When that loan matures, refinancing at a higher rate can significantly increase debt service.
For example, consider a $2 million refinance with a 25-year amortization:
Interest rate | Approximate monthly P&I |
|---|---|
4.50% | $11,117 |
6.50% | $13,504 |
8.00% | $15,436 |
Illustrative calculations; actual payments depend on loan terms.
Moving from 4.50% to 8.00% increases monthly principal and interest by approximately $4,319.
That additional debt service may reduce the property's debt service coverage ratio (DSCR) and its ability to support the desired loan amount.
2. Lower Property Values
Commercial property values are often influenced by net operating income (NOI) and capitalization rates.
Consider a property generating $200,000 in annual NOI.
At a 5.5% capitalization rate:
Estimated value = $3,636,364
At a 7.0% capitalization rate:
Estimated value = $2,857,143
That represents an estimated value decline of approximately $779,221, even though NOI has not changed.
If the property's value has declined, the lender's maximum loan-to-value (LTV) requirements may limit refinancing proceeds.
3. Reduced Cash Flow
Vacancy, tenant turnover, rising insurance premiums, property taxes, repairs, and operating expenses can reduce NOI.
Since commercial lenders frequently underwrite the property's cash flow, reduced NOI may lead to a smaller approved loan amount.
4. Tighter Underwriting Standards
Depending on the lender and loan program, underwriting may consider:
Debt service coverage ratio
Loan-to-value ratio
Debt yield
Borrower liquidity and net worth
Tenant quality and lease expirations
Property condition and market performance
Sponsor experience and credit history
A property that qualified for financing five years ago may not qualify for the same loan amount today.
Seven Critical Steps to Take Six Months Before Commercial Loan Maturity
Step 1: Review Your Existing Loan Documents
Before pursuing refinancing, understand exactly what your current loan requires.
Review the promissory note, loan agreement, and applicable amendments.
Identify the maturity date, outstanding principal balance, interest rate, payment structure, and any extension provisions.
Also review:
Prepayment penalties
Yield maintenance or defeasance provisions
Extension notification deadlines
Extension fees and conditions
Recourse provisions
Reserve requirements
Default and maturity-related provisions
Some commercial loans provide extension options, but those extensions may be subject to strict requirements.
Important: An extension is not necessarily automatic. Contact your existing lender early to determine what options may be available.
Step 2: Update Your Property Financials
Commercial lenders want to understand the property's current and historical financial performance.
Start assembling a complete refinancing package.
Documents commonly requested include:
Current rent roll
Trailing 12-month operating statement (T-12)
Prior two or three years of operating statements
Current-year profit and loss statement
Existing loan statement
Property insurance information
Real estate tax information
Copies of major leases
Schedule of capital improvements
Personal financial statement
Borrower liquidity documentation
For owner-occupied commercial real estate, lenders may also require business financial statements, tax returns, and other operating information.
A well-organized package can help lenders evaluate the transaction more efficiently.
Step 3: Calculate Your Current DSCR
The debt service coverage ratio is one of the most important metrics in commercial mortgage underwriting.
DSCR = Net Operating Income ÷ Annual Debt Service
Suppose your commercial property generates $180,000 in annual NOI.
If proposed annual debt service is $144,000:
DSCR = $180,000 ÷ $144,000 = 1.25x
This means the property generates $1.25 of NOI for every $1.00 of annual debt service.
Many conventional commercial lenders seek a DSCR around 1.20x to 1.30x or higher, depending on property type, risk, and loan program.
If the property's DSCR falls below the lender's minimum requirement, the borrower may need to reduce the loan amount, contribute additional equity, or explore alternative financing.
Step 4: Determine How Much Loan Your Property Can Support
One of the biggest refinancing mistakes is assuming that a new lender will automatically refinance the entire existing loan balance.
Commercial loan proceeds are frequently constrained by multiple underwriting metrics.
Consider a property with:
Estimated value: $3,000,000
Annual NOI: $210,000
Existing loan balance: $2,100,000
At 70% LTV, the maximum loan would be $2,100,000.
However, suppose the lender requires a minimum 1.25x DSCR and uses a 7.50% interest rate with 25-year amortization.
The maximum annual debt service would be:
$210,000 ÷ 1.25 = $168,000
Under those illustrative financing terms, DSCR would support approximately $1.89 million in loan proceeds.
That creates a potential refinancing shortfall of approximately $210,000 before closing costs, reserves, and other adjustments.
The key lesson: Property value alone does not determine commercial refinancing proceeds.
Your property's cash flow must also support the debt.
Step 5: Compare Multiple Commercial Financing Options
Commercial property owners should evaluate several potential refinancing solutions rather than relying exclusively on their existing lender.
Possible options include:
Traditional Banks
Banks may offer competitive financing for stabilized commercial properties and qualified borrowers.
Credit Unions
Some credit unions provide commercial real estate financing with attractive structures for qualifying properties and borrowers.
Debt Funds
Debt funds may offer financing for transitional properties, lease-up situations, or transactions that do not meet conventional bank requirements.
CMBS Financing
Commercial mortgage-backed securities financing may be appropriate for certain stabilized income-producing properties, subject to program size and underwriting requirements.
Agency Multifamily Financing
Eligible apartment properties may qualify for financing through Fannie Mae or Freddie Mac programs.
SBA Financing
Qualifying owner-occupied business properties may be eligible for SBA 7(a) or SBA 504 financing, subject to eligibility and program requirements.
Bridge Financing
A bridge loan may provide additional time to stabilize occupancy, complete renovations, improve operating performance, or prepare for permanent financing.
Bridge financing generally carries different pricing, fees, and maturity risks than long-term conventional financing.
Each option should be evaluated based on more than the quoted interest rate.
Compare loan proceeds, term, amortization, recourse, fees, prepayment provisions, and exit strategy.
Step 6: Develop a Backup Plan
Not every property will qualify for sufficient refinancing proceeds.
That does not necessarily mean the owner has no alternatives.
Potential strategies include:
Negotiating an extension with the current lender
Contributing additional equity
Bringing in a qualified capital partner
Pursuing a bridge loan
Improving occupancy and NOI
Selling the property before maturity
Evaluating a negotiated loan modification
Each strategy has financial and legal considerations.
For example, a short-term extension may provide additional time, but it may also involve fees, additional collateral, or new lender requirements.
The goal is to identify potential solutions before maturity creates a time-sensitive problem.
Step 7: Work With a Commercial Mortgage Advisor Early
Commercial refinancing can involve multiple lenders, underwriting standards, and financing structures.
Working with an experienced commercial mortgage advisor can help property owners evaluate which financing options may fit their particular circumstances.
Through the CommLoan Empower Program, I help commercial real estate investors and business owners evaluate financing alternatives and prepare their transactions for lender review.
CommLoan's CUPID™ commercial lending marketplace provides access to a network of more than 700 lenders, helping advisors identify potential financing options based on the transaction's characteristics.
The objective is not simply to find the lowest advertised interest rate.
It's to identify a financing structure that addresses the property's cash flow, existing debt, borrower objectives, and long-term investment strategy.
Your Commercial Loan Maturity Timeline
Here's a practical six-month refinancing roadmap.
Time before maturity | Recommended action |
|---|---|
6 months | Review loan terms, contact existing lender, gather financials |
5 months | Analyze NOI, DSCR, LTV, debt yield, and refinancing feasibility |
4 months | Compare financing options and begin lender discussions |
3 months | Advance applications, underwriting, appraisal, and due diligence |
2 months | Address lender conditions and evaluate backup strategies |
1 month | Finalize closing requirements or implement a negotiated alternative |
This is a planning framework, not a guaranteed closing schedule. Complex transactions may require substantially more time.
What If Your Commercial Loan Cannot Be Refinanced?
If your property cannot support enough new debt to pay off the existing mortgage, you may face a refinancing gap.
For example:
Existing loan payoff: $2,500,000
Maximum available refinancing: $2,100,000
Refinancing shortfall: $400,000
The borrower must develop a strategy to address that shortfall.
Possible solutions include contributing equity, negotiating with the current lender, obtaining additional permissible capital, or selling the property.
Waiting until the maturity date to confront the shortfall can significantly reduce your flexibility.
Early planning creates more time to evaluate alternatives.
Frequently Asked Questions About Commercial Loan Maturity
Can I refinance my commercial mortgage before it matures?
Yes. Many commercial loans can be refinanced before maturity, subject to loan terms, prepayment restrictions, lender approval, and transaction economics.
What happens if I cannot pay my commercial balloon payment?
Failure to repay a loan at maturity may constitute a default, potentially allowing the lender to pursue remedies under the loan documents and applicable law. Contact your lender promptly and seek appropriate legal and financial advice.
How early should I start refinancing a commercial loan?
Starting six to twelve months before maturity can be prudent, particularly for larger, complex, or transitional properties.
Can I extend my existing commercial mortgage?
Possibly. Some loans include contractual extension options, while other extensions require a separate negotiation with the lender.
Can I refinance a commercial property with high vacancy?
Potentially. Financing availability depends on occupancy, cash flow, property value, borrower strength, and the selected loan program. Some transitional lenders may consider properties that conventional lenders cannot finance.
What if my property value has declined?
You may need additional equity, a different financing structure, or a negotiated solution with the existing lender. The appropriate strategy depends on the size of the shortfall and the property's prospects.
Final Thoughts: Don't Wait Until Your Commercial Loan Matures
A commercial loan maturity date should not come as a surprise.
Whether you own an apartment building, retail center, office property, industrial facility, or owner-occupied commercial building, preparing early can make a meaningful difference.
The most important steps are straightforward:
Understand your existing loan terms.
Update your property's financial information.
Determine how much financing the property can support.
Compare multiple commercial lending options.
Establish a backup plan before maturity.
If your commercial real estate loan matures in the next six months, now is the time to evaluate your options.
Let's Discuss Your Commercial Refinancing Strategy
I'm Bill Rapp, CCIM, with the CommLoan Empower Program.
I help commercial real estate investors and business owners evaluate their financing needs and identify potential lending solutions.
Whether you're facing an upcoming balloon payment, refinancing a stabilized property, or dealing with a challenging maturity, let's evaluate the numbers and explore your options.
Explore Commercial Financing:https://billrapp.commloan.com/
Schedule a Consultation:https://calendly.com/vikingenterprise
Disclaimer: This article is for educational purposes only and does not constitute a loan commitment or guarantee of financing. Loan availability, rates, terms, eligibility, and underwriting requirements vary by lender and transaction.