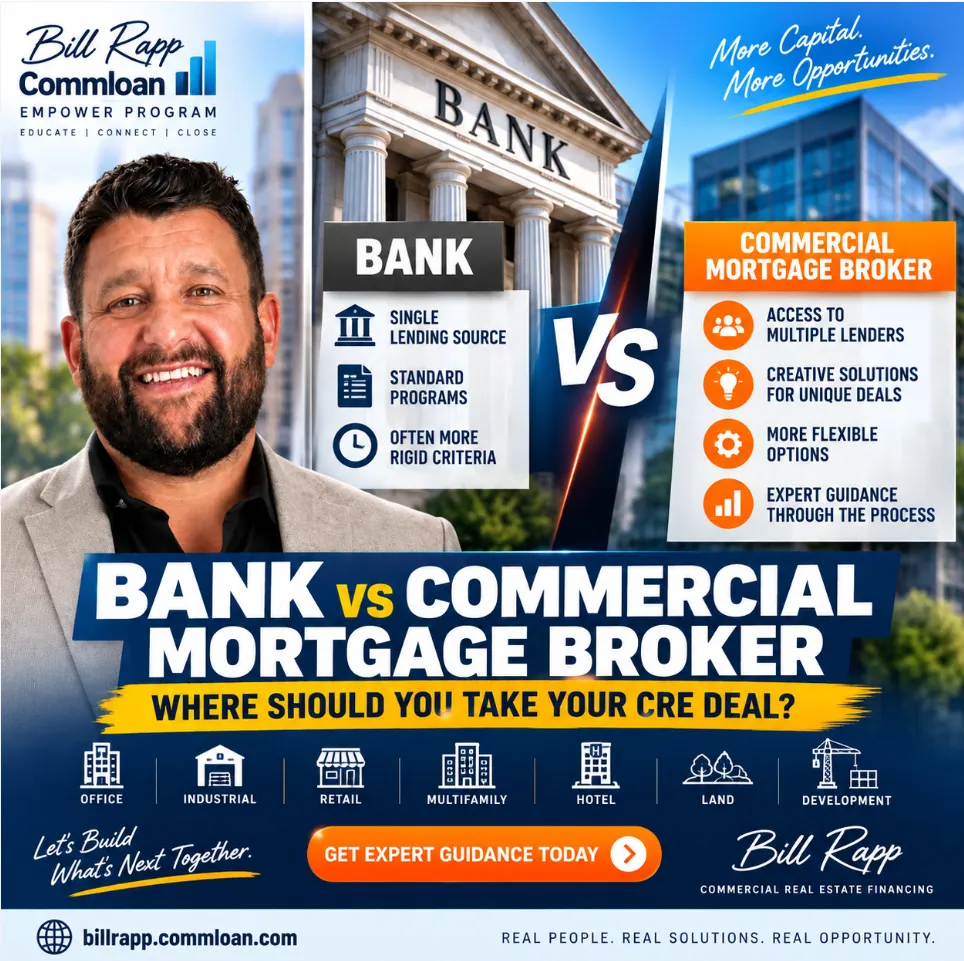
🏦 Bank vs. Commercial Mortgage Broker: Where Should You Take Your CRE Deal? 🏢
🏦 Bank vs. Commercial Mortgage Broker: Where Should You Take Your CRE Deal? 🏢
💰 Commercial Real Estate Financing: Bank Loan or Commercial Mortgage Broker? 🔑
________________________________________________________________________________
Bank vs. Commercial Mortgage Broker: Where Should You Take Your CRE Deal?
When you need commercial real estate financing, one of the first decisions is where to take the deal.
Do you walk into your existing bank and apply for a commercial real estate loan?
Or do you work with a commercial mortgage broker who can evaluate the transaction and seek financing from multiple potential capital sources?
There is no universal answer. Banks and commercial mortgage brokers serve different functions, and the right approach depends on the property, borrower, transaction structure, timing, leverage, cash flow, and overall financing objective.
The key is understanding the difference before you commit to a financing strategy.
What Happens When You Take a CRE Deal Directly to a Bank?
A bank evaluates your commercial real estate transaction against its own lending criteria.
That can include:
·Property type
·Loan size
·Loan-to-value ratio (LTV)
·Debt service coverage ratio (DSCR)
·Borrower liquidity
·Net worth
·Credit history
·Guarantor strength
·Geographic footprint
·Deposit relationship
·Industry concentration
·Loan concentration
·Amortization and maturity requirements
If your transaction fits the bank's credit box, a direct bank relationship can work very well.
This can be especially true when you already have a strong banking relationship, the property and borrower fit conventional underwriting standards, and the bank is actively lending on that particular type of transaction.
But there is an important distinction:
A bank can generally offer you the financing solutions available from that bank.
That is different from evaluating the deal across a broader commercial lending market.
What Does a Commercial Mortgage Broker Do?
A commercial mortgage broker or capital advisor approaches the transaction from a different direction.
Rather than asking:
"Does this deal fit our bank?"
The question becomes:
"What type of lender and financing structure best fits this transaction?"
Depending on the deal, potential capital sources can include:
·Banks
·Credit unions
·SBA lenders
·Agency lenders
·CMBS lenders
·Debt funds
·Bridge lenders
·Life insurance companies
·Private lenders
·Specialty finance companies
·Other commercial real estate capital sources
That broader perspective can become particularly valuable when a transaction doesn't fit neatly inside one lender's underwriting box.
Bank vs. Commercial Mortgage Broker: The Fundamental Difference
Think about the difference this way.
A bank is a source of capital.
A commercial mortgage broker is a source of potential capital relationships and financing strategies.
That does not automatically make one approach better than the other.
A strong local bank may provide exactly the financing you need.
But when the transaction is complicated—or when you want to understand alternatives—a commercial mortgage broker can help determine which lenders may be appropriate for the opportunity.
When Going Directly to a Bank Can Make Sense
A direct bank relationship can be attractive when you have a relatively straightforward transaction.
For example, imagine a business owner purchasing the building their company has occupied for several years.
The business has strong historical cash flow, the borrower has excellent liquidity and credit, leverage is conservative, and the borrower already has a substantial relationship with a local bank.
That may be an excellent bank transaction.
Existing relationships can matter in commercial lending. A bank that understands your business, financial history, deposits, and management team may be comfortable underwriting a transaction that fits its credit standards.
When a Commercial Mortgage Broker Can Add Value
Now consider a different transaction.
An investor is purchasing a property with:
·Significant vacancy
·Near-term lease rollover
·Planned renovations
·An aggressive closing deadline
·Transitional cash flow
·A request for higher leverage
One bank might decline the transaction because of occupancy.
Another lender might consider it but reduce proceeds because of DSCR.
A bridge lender might evaluate the transaction based on the stabilization strategy.
Another institution might have an attractive program but require different reserves or sponsorship strength.
This is where commercial mortgage brokerage and capital advisory can become particularly useful.
The problem isn't necessarily that the transaction cannot be financed.
The challenge may be identifying the right capital source for the transaction.
Commercial Real Estate Financing Is More Than Finding the Lowest Rate
Borrowers naturally focus on interest rates.
Rates matter.
But the lowest advertised rate does not automatically produce the best financing structure for a particular transaction.
Commercial borrowers should also evaluate:
Loan proceeds. How much will the lender actually advance?
Amortization. Is the loan amortized over 20, 25, or 30 years?
Maturity. Is the loan due in five, seven, or ten years?
Recourse. Will personal guarantees be required?
Prepayment provisions. Is there a declining prepayment penalty, yield maintenance, defeasance, or another restriction?
Reserves. Will the lender require replacement, tax, insurance, tenant improvement, or leasing commission reserves?
Covenants. What ongoing financial requirements will apply?
Closing timeline. Can the lender realistically meet the transaction deadline?
A slightly lower interest rate can lose much of its appeal if the structure doesn't accomplish the borrower's actual objective.
Why Lender Fit Matters
Commercial lenders do not evaluate every property type equally.
A lender that aggressively finances stabilized multifamily properties may have little appetite for hotels.
A bank comfortable with owner-occupied industrial buildings may not want a partially vacant retail center.
A lender interested in $2 million loans may have little interest in a $20 million request—and vice versa.
Lending appetite can also change.
Banks manage concentrations. Capital markets move. Credit policies change. Property types move in and out of favor.
That means a lender that financed your last transaction may not necessarily be the right lender for your next one.
The Three Numbers That Can Limit Your Loan
Commercial real estate investors should understand three particularly important underwriting metrics:
Loan-to-Value Ratio
LTV = Loan Amount ÷ Property Value
A lender offering 75% LTV does not necessarily mean you will receive 75% financing.
Debt Service Coverage Ratio
DSCR = Net Operating Income ÷ Annual Debt Service
Even when the property's value supports the requested loan, cash flow must generally support the associated debt service under the lender's underwriting requirements.
Debt Yield
Debt Yield = Net Operating Income ÷ Loan Amount
Debt yield allows lenders to evaluate property income relative to loan exposure without relying directly on interest rate or amortization.
Depending on the lender and transaction, one of these tests may become the binding constraint on proceeds.
That is why asking "What's your maximum LTV?" is often only the beginning of the financing discussion.
Should You Shop Your CRE Loan Yourself?
You certainly can.
But commercial financing isn't always comparable to requesting three identical mortgage quotes.
Different lenders may underwrite NOI differently, offer different amortization periods, require different reserves, calculate DSCR differently, or have completely different appetites for the same property.
Submitting a transaction indiscriminately to numerous lenders can also create unnecessary confusion.
Effective commercial mortgage brokerage isn't simply sending a loan request everywhere.
It is matching the transaction to lenders whose programs and credit criteria make sense for the deal.
What Information Should You Prepare?
Whether you approach a bank directly or work with a commercial mortgage broker, preparation matters.
For an investment property, lenders commonly want information such as:
·Purchase contract or loan statement
·Current rent roll
·Historical operating statements
·Property financial projections when applicable
·Personal financial statement
·Schedule of real estate owned
·Borrower liquidity information
·Organizational documents
·Property information
·Sponsor experience
For owner-occupied properties, underwriting may also require:
·Business tax returns
·Interim profit-and-loss statements
·Balance sheets
·Business debt schedules
·Ownership information
·Business projections when applicable
The cleaner the financing package, the easier it becomes to identify potential problems before they threaten the transaction.
Financing Should Start Before the Purchase Contract
One of the biggest mistakes commercial buyers make is treating financing as an afterthought.
A property may appear affordable based on purchase price alone.
But lender requirements for DSCR, LTV, liquidity, reserves, debt yield, guarantor strength, and property condition can materially affect how much capital is available.
Understanding those constraints before making an offer can improve your negotiating position and reduce the chance of discovering a financing gap after going under contract.
Bank or Commercial Mortgage Broker?
The better question may be:
How straightforward is the transaction, and how much of the commercial lending market do you need to evaluate?
A strong bank relationship can be extremely valuable.
A commercial mortgage broker can be valuable when you need broader lender access, help evaluating structures, a solution for a more complicated transaction, or assistance navigating the commercial financing process.
And these approaches aren't necessarily mutually exclusive.
A qualified capital advisor may ultimately determine that a bank is the appropriate destination for your transaction.
The objective isn't to avoid banks.
The objective is to get the right CRE deal in front of the right capital source.
Start With the Deal, Not the Lender
Before deciding where to take your next commercial real estate transaction, start with the fundamentals:
What are you buying or refinancing?
How much financing do you need?
What does the property's cash flow support?
How much equity and liquidity do you have?
What is your timeline?
What are you ultimately trying to accomplish?
Once those questions are answered, you can build the financing strategy around the transaction instead of trying to force the transaction into a predetermined lending box.
I'm Bill Rapp with the CommLoan Empower Program. If you're buying, refinancing, or repositioning commercial real estate, let's evaluate the deal and determine what financing strategy may fit the opportunity.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan